Source: Adobe Stock Author: Redaction What is the CPCV? The Promissory Purchase and Sale Contract (CPCV) is the agreement through which the buyer and seller undertake to subsequently enter into the definitive purchase and sale contract for the property. Although it is not mandatory in all transactions, it is frequently used when the deed cannot yet be completed, for example, while the buyer is awaiting financing or when certain procedures still need to be completed. The contract must identify the parties, the property, the price, the payment terms, the deadline for the definitive purchase and sale and the consequences of any breach of contract. What should the contract include? Before signing a CPCV, it is important to check that the document includes, among other elements: Full identification of the buyer and seller; Property details and characteristics; Price and payment terms; Amount and conditions of the deposit, where applicable; Deadline for completing the definitive contract; Conditions relating to financing, works or other specific circumstances; Consequences in the event of breach of contract; Equipment or other items included in the sale. The propertys status in the Land Registry, as well as the applicable tax and planning information, should also be checked. Is a deposit mandatory? No. The law does not establish a fixed percentage for the deposit, although it is common for the buyer to pay an amount as part of the CPCV. The amount must be expressly stated in the contract. The deposit also has specific consequences in the event of breach of contract: depending on the circumstances, the seller may retain the deposit or the buyer may demand its repayment in double. In certain circumstances, it may also be possible to seek specific performance through the courts in order to require the definitive contract to be completed. What documents should be checked? The required documentation depends on the property and the transaction. Relevant documents may include the Land Registry, tax records and applicable planning documentation. It is important to take into account the changes introduced by the Urban Planning Simplex. Since 2024, the presentation of the Housing Technical File and the occupancy permit has no longer been required at the time of transferring ownership of the property. Planning rules were subsequently amended again in 2026, so the applicable documentation should be confirmed in each case. Precautions before signing a CPCV Before signing, check: Who the owner is and whether there are any liens or charges on the property; Whether the property details are correct; The price, deposit and payment terms; The deadline for completing the definitive contract; The conditions relating to financing, where applicable; What is included in the sale; The consequences of any breach of contract. The CPCV should clearly reflect everything agreed between the parties. In case of doubts or complex situations, it is advisable to seek specialist legal advice. This article is for information purposes only and does not replace advice from a qualified professional.
Source: Adobe Stock Author: Redaction What sets each mortgage rate apart? When taking out a mortgage, one of the most important decisions is choosing between a fixed, variable or mixed interest rate. This choice affects your monthly repayment, the impact of interest rate fluctuations and the total cost of the loan over time. Each option has its own characteristics and may be more suitable depending on your financial profile, the evolution of the Euribor and your home financing goals. Fixed, variable and mixed rates: what are the differences? A fixed rate keeps your monthly repayment unchanged throughout the entire loan term, regardless of changes in interest rates. This option offers predictability and makes household budgeting easier, although it generally comes with a higher initial rate and does not benefit from any fall in the Euribor. A variable rate is linked to the Euribor and is usually reviewed every three, six or twelve months. Whenever this benchmark rises or falls, your repayment changes accordingly. During periods of low interest rates, it can result in lower monthly payments, but it also carries greater risk when rates increase. A mixed rate combines both models. A fixed rate applies for an agreed initial period, after which the loan automatically switches to a variable rate. This solution has consolidated itself as the predominant choice in the Portuguese market, driven by highly competitive 1, 2, and 3-year bank offers that provide immediate relief on monthly repayments amidst the stabilization of Euribor rates. How do you choose the best option? The decision depends on several factors, including your financial capacity, job stability and tolerance for risk. If you want to know exactly how much you will pay each month, a fixed rate may be the most suitable option. If you expect the Euribor to fall in the future and can cope with possible increases in repayments, a variable rate may be more appropriate. A mixed rate offers a balanced alternative for those seeking initial stability while retaining the possibility of benefiting from future market developments. It is also important to consider your debt-to-income ratio, the loan term and the possibility of making early repayments. Comparing offers can save you money Before taking out a mortgage, it is advisable to request quotations from several lenders and compare indicators such as the APRC, the Total Amount Payable, the spread and insurance costs. Practical example : Imagine a family taking out a €200,000 mortgage over 35 years. By opting for a fixed or mixed rate, they manage to shield their monthly repayment against potential Euribor increases during the initial years, ensuring the household budget faces no unexpected fluctuations. On the other hand, choosing a variable rate leaves you exposed to the indexers semi-annual or annual reviews, benefiting immediately if interest rates fall, but taking on the risk of higher monthly repayments if inflation puts pressure on European Central Bank rates again.
Source: Adobe Stock Author: Redaction Public guarantee can make borrowing easier The public guarantee allows banks, in certain circumstances, to finance up to 100% of the purchase value of a first permanent home. The aim is to reduce one of the main obstacles faced by those looking to buy a home: raising the money needed for the initial deposit. However, this measure does not mean that the State provides the mortgage loan. The loan is still granted by the bank, which assesses the buyers income, employment stability, debt-to-income ratio, credit history and other financial commitments. Therefore, even with a public guarantee, buyers must demonstrate that they can afford the repayments throughout the loan term. Tax exemption reduces initial costs In addition to the financing guarantee, there are tax benefits for young people buying their first permanent home. Provided they meet the applicable requirements, buyers may benefit from an exemption from IMT and Stamp Duty on the purchase of the property. The latter is equivalent to 0.8% of the purchase price. However, the exemption does not cover all taxes associated with the transaction. Stamp Duty on bank financing, corresponding to 0.6% of the amount financed, is still payable, as are other costs related to the purchase. How much can a young buyer save? Imagine buying a home for €220,000. Without these support measures, a 90% mortgage would generally require around €22,000 for the deposit, in addition to taxes and other costs associated with the deed. With the public guarantee, and provided the applicable conditions are met, the buyer may be able to obtain financing of up to 100%, significantly reducing the amount of their own capital required. The possible exemption from IMT and Stamp Duty on the purchase can further reduce the initial costs. However, there are still costs associated with the financing and completing the purchase. Support does not eliminate borrowing costs Despite the assistance available, buying a home remains a long-term financial commitment. Monthly repayments, insurance associated with the mortgage loan and other costs should be taken into account before proceeding. The maximum amount the bank is willing to finance does not necessarily mean that it is the most suitable amount for the household budget. A lower monthly payment can provide greater financial flexibility for unexpected expenses and savings. The support measures can therefore make it easier for young people to access their first home, but it is important to carefully assess the financing conditions and the ability to cover the costs over the years.
Source: Adobe Stock Author: Redaction Why are mixed-rate mortgages the preferred option in Portugal? The search for greater stability during the first years of a mortgage continues to shape families decisions. According to the latest data from the Bank of Portugal, mixed-rate mortgages reached another record, accounting for more than 85% of new loans for owner-occupied housing. This option, which combines an initial fixed-rate period with a later stage indexed to the Euribor, has established itself as the main safeguard against market volatility. Across the housing loan market, the average interest rate on new contracts stood at 2.93%. Variable-rate offers recorded a slight increase, while fixed-rate solutions registered a small decline. The conditions offered to new customers and those applied in renegotiation processes are also becoming increasingly similar. What is changing in monthly repayments and new lending? Despite the clear dominance of mixed-rate mortgages, the total amount granted for home purchases slowed, with the overall volume of new lending and renegotiations falling below the previous months level. Even so, borrowing costs remain under pressure: the average monthly housing loan repayment continued to rise, driven both by updates to existing contracts and by the financial conditions of new loans. In contrast to housing loans, the consumer credit segment recorded a slight increase over the same period. What is happening with savings and term deposits? In terms of savings, term deposits recorded a fifth consecutive increase in their average interest rate. However, the returns offered by Portuguese banks remain below the Eurozone average. After a strong start to the year in new deposits, the pace of new household savings has stabilised.
Source: Adobe Stock Author: Redaction Mortgage payments increase as Euribor rises Mortgage payments will increase again in August following the rise in Euribor rates during July. The three main maturities all ended above 2.4%, with the 12-month Euribor standing out at 2.855%, its highest level since the end of 2024. Although the European Central Bank kept its key interest rates unchanged at its latest meeting, instability in international markets and expectations of further interest rate hikes contributed to the rise in Euribor. This means higher borrowing costs for those taking out a new mortgage, as well as for existing borrowers with variable-rate loans. Mortgage lending faces new restrictions In addition to higher mortgage payments, buyers are also facing stricter lending rules. Since August, the maximum debt-to-income ratio considered by banks has been reduced to 45%, limiting access to mortgage financing. This change may restrict the approval of new loans, particularly for households with lower incomes. At the same time, rising interest rates continue to put pressure on household budgets, making home purchases more challenging. For borrowers with mortgages indexed to Euribor, the reviews scheduled for August are also expected to reflect higher repayments than in previous revisions, in line with the increase in benchmark rates. How to reduce the impact of mortgage payments In this context, there are several ways to reduce the impact of higher mortgage payments. Available options include renegotiating the spread with the bank, switching to a mixed or fixed-rate mortgage, or transferring the mortgage to another financial institution offering more competitive conditions. The size of the increase will always depend on the outstanding loan balance, the remaining loan term and the chosen index. Even so, reviewing mortgage conditions regularly may help borrowers find more favourable alternatives. Anyone planning to buy a home should consider not only the propertys value but also interest rate trends and the stricter lending requirements to ensure a financially sustainable decision in the long term.
Source: Adobe Stock Author: Redaction What are hidden defects in properties? Hidden defects in properties are faults that already existed at the time of purchase but were not visible during a normal inspection. Problems such as leaks, cracks, plumbing faults, electrical issues or insulation defects may only become apparent after the property has been occupied for some time. In addition to the inside of the property, these defects may also affect external elements, such as façades, roofs, balconies or waterproofing systems. When it is proven that the problems already existed before the purchase, the buyer may hold the seller or the developer liable under Portuguese law. How should you deal with hidden defects in properties? If you identify hidden defects in properties, it is important to act quickly. To protect your rights, follow these steps: Gather all the evidence: take photographs and videos of the defects, document the affected areas and, whenever possible, obtain a technical report from an engineer or specialist surveyor identifying the cause and extent of the problem. Notify the seller or developer: send a formal notification by registered post with acknowledgement of receipt or by another method that provides proof of communication. Describe the defects found, state when they appeared and request that they be repaired within a reasonable period. Try to reach an agreement: whenever possible, seek an amicable solution. This may include repairing the defects, replacing damaged elements or agreeing on appropriate compensation, avoiding lengthy legal proceedings. Seek legal advice if necessary: if no agreement can be reached or the responsible party refuses to accept liability, you may need to consult a solicitor specialising in property law to defend your rights. What are the deadlines for making a claim? Portuguese law establishes specific deadlines for claiming hidden defects in properties. After discovering the defect, the buyer has up to one year to notify the seller. Following that notification, there is a further six-month period to bring legal action if no solution is reached. For new properties purchased directly from developers or builders, construction warranties may also apply, particularly in cases involving structural defects, with protection lasting for several years. The sooner you report the problems, the greater the chances of resolving the situation quickly and preventing further damage. How can you reduce the risk before buying a property? Although not every issue can be anticipated, there are several measures that help reduce the risk of buying a property with hidden defects. Before purchasing, it is advisable to check the reputation of the builder or seller, review the propertys documentation and confirm that all the relevant licences are in place. It may also be useful to commission an independent building inspection to assess the propertys structure, electrical installations, plumbing and other essential elements. This assessment can identify potential defects before the contract is signed. Taking these precautions can help avoid unexpected expenses in the future and provide greater security throughout the property purchase process.
Source: Adobe Stock Author: Redaction Mortgage lending faces new restrictions Banks expect a more demanding period for mortgage lending, forecasting stricter lending criteria and a decline in demand from households. The conclusions come from the latest survey published by the Bank of Portugal, which points to a less dynamic market in the coming months. Following the strong growth recorded last year, financial institutions expect a slowdown in mortgage lending. Among the factors behind this change are international economic uncertainty, rising interest rates and the entry into force of the new macroprudential rules established by the supervisor. Banks tighten lending criteria Over the past three months, banks have already made the criteria for approving mortgage lending more stringent. Financial institutions justify this decision with the economic outlook, expected developments in the housing market and forecasts for house prices. According to the Bank of Portugal, this trend is expected to continue over the coming months. In contrast, banks do not anticipate significant changes to lending conditions for consumer credit and other types of financing. Household demand is expected to continue falling Demand for mortgage lending recorded a slight decline in the last quarter, reflecting the impact of tighter financial conditions and stricter requirements imposed by banks. Forecasts indicate that this trend will continue over the coming months as the market adapts to the new economic and regulatory environment. With stricter criteria and a more demanding financial context, banks expect a more moderate pace in mortgage lending.
Source: Adobe Stock Author: Redaction Climate risks influence home-buying decisions Climate risks are becoming increasingly important in the decisions of people looking to buy a home. In Portugal, 87% of consumers consider exposure to extreme weather events to be an important or very important factor when choosing a property. According to a study by the Observador Cetelem, storms, strong winds and local tornadoes are the main concern for 48% of respondents. Heatwaves rank second, cited by 40% of Portuguese people, while cold comes third, followed by wildfires and flooding. The growing frequency of these events is leading more and more families to assess the location and resilience of properties before buying. Portuguese people question the resilience of their homes Despite the importance given to climate risks, only 62% of Portuguese people believe their home is prepared to withstand extreme weather events, a figure below the European average. Even so, most respondents consider their home to provide a satisfactory level of day-to-day comfort. The data also reveal that only a small percentage of residents are completely satisfied with their homes ability to cope with these challenges. In addition, more than half believe they are exposed to two or more climate risks, reflecting growing concerns about the safety and resilience of the housing stock. Cold remains one of the biggest challenges Cold continues to be one of the main issues identified by Portuguese households, with a percentage above the European average. By contrast, satisfaction with home comfort during spring and summer remains high, highlighting seasonal differences in perceptions of well-being. This reality shows that factors such as thermal insulation, ventilation and construction quality are playing an increasingly important role in property value. Housing adapts to new demands Growing concern about climate risks is changing home-buying criteria. Alongside location, price and energy efficiency, buyers increasingly value properties capable of withstanding extreme weather events and providing better living conditions. This trend is expected to continue shaping the property market, encouraging more resilient construction solutions and a gradual adaptation of the housing stock to changing climate conditions.
Source: Adobe Stock Author: Redaction Mortgage interest rates rise again Mortgage interest rates reversed the downward trend seen in recent months and increased again in June. According to data from the National Statistics Institute (INE), the implicit interest rate across all mortgage contracts rose to 3.101%, up from 3.065% in May, interrupting the previous downward trajectory. This change follows the European Central Banks (ECB) decision to raise its key interest rates in June and also reflects the increase in Euribor, the main benchmark for mortgage loans in Portugal. The impact is now beginning to be felt in both existing contracts and new loans. For contracts signed in the last three months, the interest rate also increased, rising from 2.820% to 2.853%, meaning higher borrowing costs for those who recently took out a mortgage. Average mortgage repayment continues to rise The average monthly mortgage repayment reached €411, €6 more than in May and €17 more than in June 2025. Of this amount, €202 relates to interest payments and €209 to capital repayment, meaning that almost half of the monthly instalment is still allocated to interest charges. For the most recent contracts, the increase was even more significant. The average repayment reached €715, €23 more than in the previous month and around 13.5% higher than in the same month last year, reflecting the impact of rising interest rates. Outstanding mortgage debt also increases In addition to the rise in mortgage interest rates, the average outstanding mortgage balance also increased. Across all contracts, the outstanding balance reached €78,865, €608 more than in May. For mortgages taken out in the last three months, the average outstanding balance rose to €179,552, an increase of €3,747 compared with the previous month. These figures confirm that financing a home purchase remains more demanding, both for new buyers and for households with contracts subject to interest rate revisions.
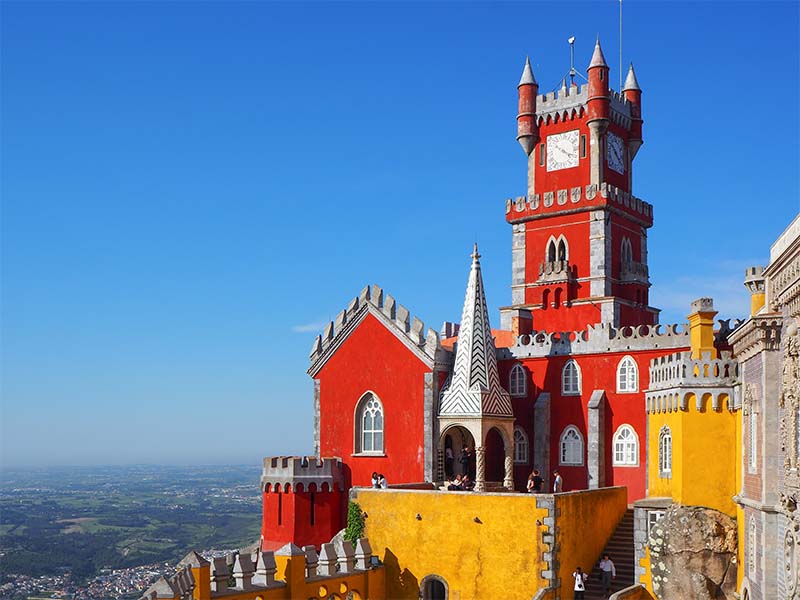
Source: Adobe Stock Author: Redaction Sintra strengthens its appeal in the property market Demand for luxury properties in Sintra grew by around 150% between 2024 and 2025, alongside an increase in the supply of homes across the region. This trend reflects the growing interest of buyers seeking alternatives to Lisbon, favouring locations that offer more space, tranquillity and easy access to the capital. Among the main factors behind this trend are the availability of villas with gardens and large plots, the preserved natural surroundings, the presence of international and private schools, and excellent accessibility. Although prices remain more competitive than in some neighbouring municipalities within the Lisbon Metropolitan Area, Sintra has experienced significant property value growth in recent years. Prices continue to rise as international interest grows According to the National Statistics Institute (INE), the median price of homes sold in Sintra reached approximately €2,733 per square metre in the fourth quarter of 2025. Prices in the luxury segment remain above this benchmark, reflecting the continued appreciation of this market. Alongside domestic demand, interest from international buyers is also increasing, particularly from the United Kingdom, Iran, South Korea and Mozambique. This demand has helped boost the high-end residential market and strengthen Sintras position as one of the most sought-after destinations for property investment. Quality of life boosts demand in Sintra The combination of historical heritage, nature, privacy and proximity to Lisbon continues to make Sintra an attractive choice for those seeking a high quality of life. Market trends show that the municipality is consolidating its position as a leading destination to live and invest, meeting the expectations of buyers looking for space, comfort and a strategic location.
Source: Adobe Stock Author: Redaction Study outlines the profile of mortgage credit intermediation A study on mortgage credit intermediaries reveals that 57.2% of transactions carried out in Portugal involve the purchase of properties valued between €250,001 and €500,000. The research, conducted by UCI in partnership with SPIRITUC – Applied Research, surveyed 733 professionals registered with the Bank of Portugal and provides a snapshot of the sector in 2026. According to the study, 37.4% of transactions involve homes worth up to €250,000, while only 5.5% exceed €500,000. In terms of financing, 45.7% of mortgage loans range between €150,000 and €250,000, followed by loans between €250,001 and €500,000, which account for 42.7% of the total. Processes take between one and two months The study also indicates that most mortgage credit processes are completed within 31 to 60 days. In many cases, however, the process can take up to 90 days from the first contact with the client to the completion of the deed. Among the main obstacles identified are the financial unfeasibility of transactions and the difficulty clients face in finding a property. Although many professionals attract more than 20 new clients per month, around half complete fewer than ten property deeds each month. Digitalisation gains ground in the sector The data also show that mortgage credit intermediaries continue to favour physical offices for customer service, although the internet is currently the main channel for attracting clients. Recommendations also continue to play an important role. The study concludes that many clients have low levels of financial literacy regarding mortgage credit, highlighting the importance of specialised guidance. Nearly half of the professionals believe that the role of credit intermediation will continue to grow over the coming years, driven by stronger brand recognition and the increasing use of digitalisation and artificial intelligence.
Source: Adobe Stock Author: Redaction What are IMT and Stamp Duty? When buying a home, in addition to the property price and the deposit for a mortgage, it is essential to take into account the mandatory taxes associated with the deed. The main ones are IMT and Stamp Duty, which form part of the total cost of the purchase. IMT is payable whenever ownership of a property is transferred through a sale, while Stamp Duty applies to the purchase and, where financing is involved, also to the amount of the mortgage loan. Understanding these obligations helps you plan your budget and avoid unexpected expenses. How are these taxes calculated? IMT is calculated based on the higher of the purchase price or the propertys Taxable Asset Value (VPT). The applicable rate varies according to the propertys location, its intended use and the type of property, with tax brackets updated annually. Stamp Duty on the purchase is charged at a rate of 0.8% on the higher of the purchase price or the VPT. If you take out a mortgage, an additional Stamp Duty of 0.6% is charged on the loan amount for contracts with terms longer than five years. Are there IMT exemptions? In certain situations, the law provides for an IMT exemption. One of the most common applies to the purchase of a primary residence, provided the propertys value falls within the legal thresholds in force. There may also be tax benefits for properties intended for urban regeneration within Urban Rehabilitation Areas (ARU), provided the legal requirements are met. Companies purchasing properties for resale may also benefit from specific tax regimes, provided they comply with the applicable rules. When must these taxes be paid? IMT and Stamp Duty relating to the purchase must be paid before or on the day of the deed, using the respective payment documents issued through the Portuguese Tax Authoritys online portal. Without proof of payment, the deed cannot be completed. In the case of Stamp Duty on a mortgage, the amount is usually collected by the bank when the loan funds are made available. Including these costs in your financial planning is essential to avoid unexpected expenses and ensure a smoother home purchase.


 English
 Português
 Français
 Español
 Deutsch
 Nederlands
 Русский
 中文(简体)